What is the market overview and industry significance of the Scan‑And‑Go Platforms Market?
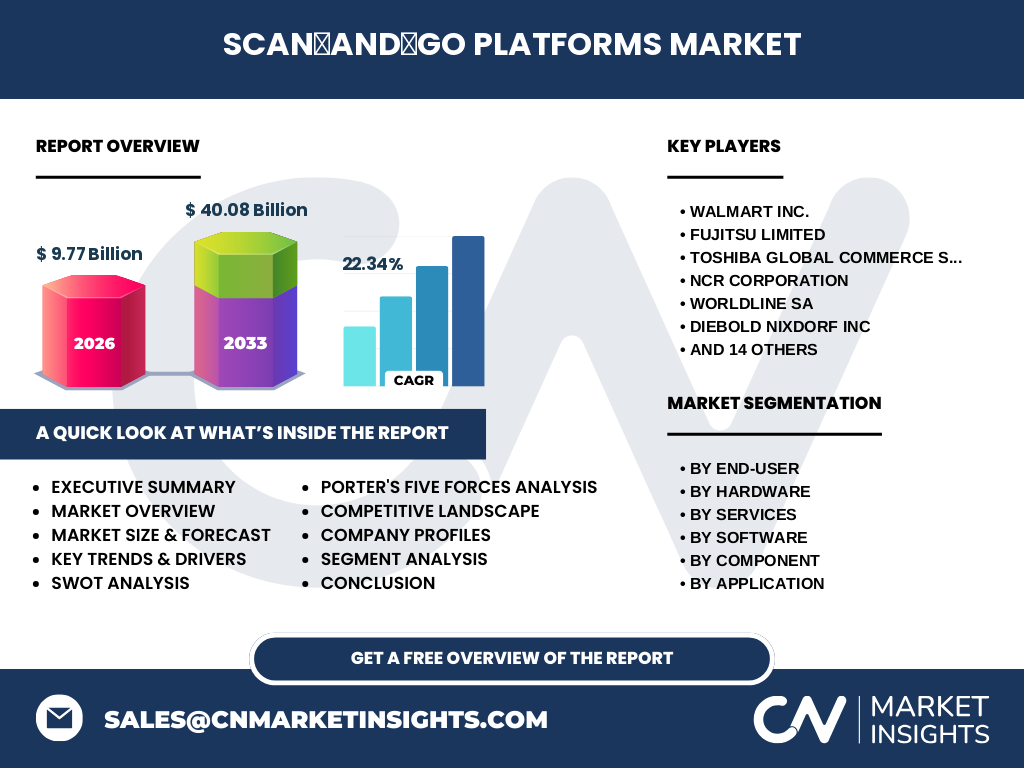
Our analysis indicates that the Scan‑And‑Go Platforms Market is valued at 9.77 Billion in 2026, revolutionizing physical retail through frictionless checkout ecosystems. Industry significance lies in eliminating front-end bottlenecks by leveraging consumer smart devices and advanced computer vision, transforming traditional brick-and-mortar operations into high-throughput digital shopping environments.
What are the key market drivers, restraints, challenges, and opportunities shaping the Scan‑And‑Go Platforms Market?
Growth is propelled by surging consumer demand for contactless shopping experiences and labor shortages in retail. However, high initial capital expenditure for Smart Shopping Carts and In Store Beacons And Sensors acts as a restraint. Data privacy compliance under regional regulations presents an ongoing operational challenge.
Emerging trends and growth patterns in the Scan‑And‑Go Platforms Market
The market is witnessing a rapid pivot toward autonomous checkout integrations, highlighted by innovators like Trigo Vision Ltd. and AiFi Inc. deploying computer-vision-driven store infrastructures. Retailers are increasingly prioritizing Cloud-Based deployment modes over legacy On-Premises architectures to accelerate cross-store scalability.
How did COVID-19 impact the Scan‑And‑Go Platforms Market and what does the recovery trajectory look like?
The pandemic served as an unprecedented catalyst, forcing merchants to fast-track touchless payment deployments to comply with social distancing mandates. Our research confirms that post-COVID recovery has permanently elevated baseline adoption, cementing mobile-driven checkout as a permanent fixture in modern retail operations.
Competitive Benchmarking: Major players, market concentration, and strategic dynamics
The competitive landscape features a blend of legacy POS giants like NCR Corporation, Fujitsu Limited, and Toshiba Global Commerce Solutions Inc. alongside agile software innovators such as Scandit AG and MishiPay Ltd. Strategic M&A and proprietary computer-vision partnerships remain core weapons for market dominance.
Executive Summary of the Scan‑And‑Go Platforms Market
Our comprehensive assessment highlights a massive valuation surge from 9.77 Billion in 2026 to 40.08 Billion by 2033, expanding at a robust CAGR of 22.34%. Retailers adopting cloud-native software and advanced mobile applications capture disproportionate market share amid escalating consumer expectations for speed.
Scan‑And‑Go Platforms Market forecast from 2027 to 2033
The market is projected to skyrocket, reaching 40.08 Billion by 2033, driven by a blistering CAGR of 22.34% from 2027 onward. This trajectory reflects widespread enterprise migration toward omnichannel retail solutions and automated loss-prevention analytics.
Segmentation Analysis of Scan‑And‑Go Platforms Market
The market segments by hardware, software, services, component, application, deployment mode, and enterprise size. Mobile Application Software and Point Of Sale Integration Software drive software demand, while Supermarkets Or Hypermarkets dominate application segments due to massive daily foot traffic and checkout congestion.
Regional market analysis and geographic distribution
Geographic performance is led by North America and Europe, supported by high smartphone penetration and robust retail IT infrastructure. Emerging economies in Asia-Pacific represent high-growth frontiers, driven by rapid urbanization and the proliferation of mobile-first payment ecosystems across metropolitan hubs.
In-depth regional review of the Scan‑And‑Go Platforms Market
North America retains the largest revenue share, fueled by early retail technology adopters and dense chain store networks. Meanwhile, European markets exhibit aggressive adoption constrained by stringent data protection frameworks, prompting localized software customization by vendors like Shopreme GmbH and Snabble GmbH.
Company Profiles and Strategic Positioning
Market leaders utilize distinct strategic angles: Walmart Inc. spearheads proprietary in-house mobile scanning applications, whereas specialists like Shopic Ltd. and SuperSmart Ltd. empower independent grocers with retrofitted smart cart hardware and real-time item recognition algorithms.
Porter's Five Forces analysis of the Scan‑And‑Go Platforms Market
Competitive rivalry is intense, driven by continuous software innovation from nimble startups and established heavyweights like Worldline SA and Diebold Nixdorf Inc. Bargaining power of buyers is moderate to high, as large retail chains demand bespoke integration capabilities and competitive SaaS pricing models.
SWOT analysis of the Scan‑And‑Go Platforms Market
Key strengths include frictionless user experiences and reduced front-end labor costs. Weaknesses stem from potential technical latency and vulnerability to shrinkage. Opportunities lie in integrating Customer Analytics And Reporting Software, while threats involve sophisticated retail theft tactics targeting mobile checkout loopholes.
Value chain analysis from software developers to end-users
The value chain originates with R&D in computer vision and payment gateway protocols, flowing through hardware manufacturers supplying Self Checkout Kiosks and Barcode Scanner s, system integrators, and finally concluding at enterprise retail end-users across supermarkets, airports, and specialized boutiques.
Investment insights and strategic recommendations
Investors should direct capital toward cloud-native Inventory Management Software and advanced computer-vision vendors. Companies partnering with major global retailers to mitigate shrinkage while enhancing shopper convenience represent prime targets for venture capital and private equity deployment.
Conclusion and key takeaways for stakeholders
The Scan‑And‑Go Platforms Market offers extraordinary growth, surging from 9.77 Billion in 2026 to 40.08 Billion by 2033. Stakeholders must prioritize seamless software interoperability and robust loss prevention mechanisms to capture long-term value in this rapidly evolving retail landscape.
Research methodology for the Scan‑And‑Go Platforms Market report
Our baseline estimates are triangulated by combining exhaustive trade registry data, primary qualitative interviews with C-level retail executives, and secondary macroeconomic indicators. We cross-reference vendor financial disclosures with retail foot-traffic analytics to ensure econometric precision and reliability.
Scope of the report and coverage parameters
This research report evaluates the Scan‑And‑Go Platforms Market across eight core segmentation axes, covering global geographic regions from 2026 through 2033. Limitations include exclusion of informal unrecorded micro-retail markets and highly localized sovereign payment gateways lacking public financial transparency.
Recent developments in the Scan‑And‑Go Platforms Market
Recent milestones include strategic rollouts by Datema Retail Solutions B.V. and Phygrid GmbH., focusing on AI-powered item recognition and frictionless store deployments. Partnerships between legacy hardware suppliers and agile mobile software providers continue to accelerate ecosystem convergence.